Paying staff and the 1601-C
Kuting Kitchen hires two staff at ₱18,000 a month. Here's one payslip worked out line by line, then the monthly 1601-C that reports the tax withheld, even when it's zero.
← 7.5 The annual returnTwo new hires
Kuting Kitchen hires two staff: Jun, a packer, and Mae, who answers customer chats. Each earns ₱18,000 a month. (The names and salaries are made up for this lesson.)
Paying a salary makes the company a withholding agent on compensation. That's why Kuting Kitchen's 2303 lists "withholding tax on compensation" (Lesson 1.2).
Start with gross pay
Mae's payslip for October 2026 starts with her basic pay: ₱18,000. That's what she earned before anything is taken out.
Everything below it is a deduction the company makes on her behalf and then pays to someone else.
Her share of SSS, PhilHealth and Pag-IBIG
First come the employee shares of the three agencies: SSS ₱900, PhilHealth ₱450 and Pag-IBIG ₱200, ₱1,550 in all. Kuting Kitchen pays its own employer share on top. Lesson 8.2 explains each one.
These shares are not taxable, so they come off before tax is worked out.
Withholding tax: ₱0 for Mae
The tax to withhold comes from BIR's withholding tax table on compensation, applied to taxable pay.
But an employee earning ₱250,000 or less for the year has nothing withheld. Mae's taxable pay is ₱16,450 a month, about ₱197,400 a year, so her tax is ₱0. A higher-paid hire would need the table.
Net pay
₱18,000 − ₱1,550 − ₱0 = ₱16,450 net pay
Mae receives ₱16,450. Jun's payslip is the same. Keep a payslip for each payday: the year-end paperwork in Lesson 8.3 adds them up.
The 1601-C: one return for the whole payroll
Every month the company files the 1601-C, the monthly remittance return of income taxes withheld on compensation. Do you file one per employee? No: one return covers everyone on the payroll.
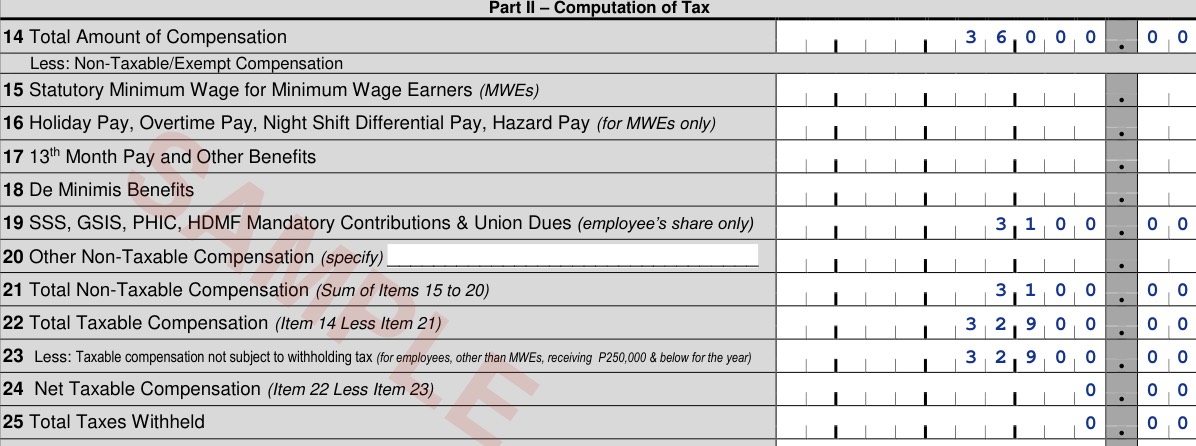
This is BIR's real form (January 2018 version), filled in for October with Jun's and Mae's pay together:
| 14 | Total compensation | ₱36,000 |
|---|---|---|
| 19 | Employee shares of SSS, PhilHealth (PHIC) and Pag-IBIG (HDMF) | ₱3,100 |
| 22 | Taxable compensation (14 less 21) | ₱32,900 |
Zero tax, still a return
Item 23 takes out pay of employees earning ₱250,000 or less a year: all ₱32,900. So item 25, taxes withheld, is ₱0, and item 3, "Any taxes withheld?", is No.
Can you skip a month with nothing withheld? No. The return is still filed: the "No" box exists so a zero month is reported, not skipped.
When it's due
| Jan–Nov | 10th of the following month: October's by 10 November 2026 |
|---|---|
| December | 15 January of the next year |
| eFPS filers | E-file on the 11th to the 15th, by filer group; pay by the 15th |
| Late | 25% surcharge, plus interest and a compromise penalty |
eFPS is BIR's Electronic Filing and Payment System. The penalties are the form's own instructions.
Pop Quiz: Liza's first payslip
Liza runs a small online shop and hires an assistant at ₱15,000 a month. The assistant's shares: SSS ₱750, PhilHealth ₱375, Pag-IBIG ₱200.
How much is withheld for income tax?
₱15,000 × 12 is ₱180,000, under ₱250,000 for the year, so nothing is withheld.
What is the assistant's net pay?
₱15,000 − ₱750 − ₱375 − ₱200 = ₱13,675. The employee shares come out of pay; the tax is ₱0.
Does Liza file a 1601-C for the month?
The 1601-C is monthly and is filed even when item 25 is ₱0 (item 3 "Any taxes withheld?" is No).

General information for learning, not tax advice. Kuting Kitchen, its staff and Liza are fictional, and the salaries are illustrative. Withholding for employees earning more than ₱250,000 a year comes from BIR's withholding tax table on compensation; confirm the current table and your filing dates with your RDO or accountant.
Ready to check what you learned?
3 quick questions on the next page. Pick an answer to see why.
Take the check →